Market Commentary Summer 2026
| GP Weston’s Summer 2026 property market report for South Somerset and North Dorset covers June to August 2026. It looks at house prices, sales agreed, new listings and price reductions across Sherborne, Yeovil, Wincanton, Castle Cary, Milborne Port and the villages in between, alongside the interest rate, mortgage and Budget news driving the wider UK housing market. This summer’s market had less to do with the usual holiday lull than with events far from the West Country. Renewed conflict in the Middle East pushed energy prices sharply higher, inflation turned back up to 3.1%, and average fixed mortgage rates rose to their highest level this year. There was also a change of Prime Minister in July, and an Autumn Budget is now set for 28 October. It is little surprise that buyers were cautious. Nationally, agreed sales are running around 9% behind last year, while the number of homes for sale has reached a 12-year high. Our own data for South Somerset and North Dorset shows the same trend, more sharply. Sellers kept coming: new instructions from June to August were only 2% down on last summer. But sales agreed fell 13% to 586, and there were more price reductions (748) than sales agreed in every month of the summer. On average, just 9.9% of available homes went under offer each month. That is the weakest summer since we began tracking the market in December 2022. There was one encouraging sign: August’s sales agreed were less than 3% below August 2025, which suggests the worst of the slowdown was in June. |
| THE NATIONAL PICTURE | |||
| +1.6% UK annual house price growth (Nationwide, Aug) | 3.75% Bank of England base rate | 5.73% Average 2-year fixed mortgage (Moneyfacts, mid-Sept) | 3.1% UK CPI inflation (August 2026) |
| OUR LOCAL MARKET — SOUTH SOMERSET & NORTH DORSET | |||
| 586 Sales agreed, Jun–Aug (−13% YoY) | 983 New instructions (−2% YoY) | 748 Price reductions (level with 2025) | 9.9% Of available homes went under offer each month |
Interest Rates, Mortgages & the UK Economy
Bank of England Interest Rates
The Bank of England has held Bank Rate at 3.75% since its last cut in December 2025. What changed over the summer was the direction of the debate. At both its July and September meetings, the Monetary Policy Committee voted 6–3 to hold rates. The three members who disagreed voted for an increase to 4%, not a cut. The Bank now expects CPI inflation to rise to around 3¾% by the end of 2026 and slightly above 4% in early 2027, and it describes the risks as “tilted to the upside”. The rate cuts many expected at the start of the year have been priced out, and some forecasters now think the next move will be up.
Mortgage Rates in 2026
For buyers, what matters more than Bank Rate is the swap rates lenders use to price fixed mortgages, and these have risen steadily. According to Moneyfacts, the average two-year fixed rate was 4.84% on 1 March, 5.63% by 1 August and 5.73% by mid-September. The average five-year fix rose from 4.96% to 5.78% over the same period. Several major lenders, including NatWest, Santander, HSBC, Lloyds and TSB, raised their rates twice in the first half of September alone. Zoopla estimates that higher mortgage costs have reduced the typical buyer’s purchasing power by around 9% since January.
Inflation & the Energy Shock
UK CPI inflation rose to 3.1% in August from 2.9% in July (ONS). Motor fuel was the biggest driver: petrol rose 9.1p a litre in August alone. The underlying cause is the conflict in the Middle East, which began on 28 February and has disrupted shipping through the Strait of Hormuz, a route for around 30% of the world’s oil. Hopes of a settlement in June did not last. Since July, Brent crude and UK wholesale gas prices have risen by 36% and 78% respectively (Bank of England). Housing costs are rising too, with owner-occupiers’ housing costs up 3.9% on the year in August.
Economic Growth, Politics & the Autumn Budget
The economy has held up better than expected, with GDP growing 0.4% in the second quarter. Politically, however, the summer brought major change. Andy Burnham became Prime Minister on 20 July and appointed John Healey as Chancellor in place of Rachel Reeves. The new Chancellor’s first Budget is scheduled for 28 October. The Prime Minister has ruled out stamp duty changes at that Budget, but the Chancellor has declined to rule out wider tax rises. Uncertainty ahead of a Budget tends to make buyers and sellers pause.
| “ There has been no shortage of sellers this summer. What has been missing is buyers with the confidence to commit, and the cause is the cost of borrowing, not any loss of appeal for the West Country. GP WESTON |
UK Housing Market: Summer 2026
UK House Prices
Price growth has been modest but positive. Nationwide recorded annual growth of 1.6% in August, up from 1.4% in July, with an average price of £275,465. The official UK House Price Index put the UK average at £273,000 in July, 1.4% higher than a year earlier, while Zoopla’s index showed growth slowing to 0.9%. Asking prices are softer. Rightmove described the summer as “particularly subdued” and September brought the first monthly rise in asking prices since May (+0.7%), but asking prices are still 0.8% lower than a year ago. The South West is lagging the national picture, with prices broadly flat on the year.
| Measure | Average price | Annual change |
| Nationwide HPI (August 2026) | £275,465 | +1.6% |
| ONS UK House Price Index (July 2026) | £273,000 | +1.4% |
| ONS — South West region (July 2026) | £302,298 | −0.2% |
| Zoopla HPI (August 2026) | £272,800 | +0.9% |
| Rightmove asking prices (September 2026) | £367,440 | −0.8% |
Sales Agreed Across the UK
Nationally, Rightmove reports agreed sales 9% lower than a year ago, with buyer enquiries also down 9%. Zoopla puts the fall at 6% but says the gap is starting to close. Buyer searches are 7% higher than a year ago, the strongest annual increase for 12 months, so interest is there even though buyers are slower to commit. On average it takes 64 days to find a buyer and a further 150 days to complete.
Homes for Sale & New Listings
New listings are 3% down on last year (Rightmove), yet the total number of homes for sale is at a 12-year high because fewer are selling. Zoopla estimates there are 5% more homes for sale than a year ago. For sellers, our advice is the same as in the spring: buyers have plenty of choice, so getting the price right from day one matters more than ever. Rightmove found that 74% of homes sold in 2026 did so without needing a price reduction.
South Somerset & North Dorset: House Prices & Market Data
Somerset and Dorset House Prices
The latest official figures, for July 2026, show Somerset outperforming the region. The average price rose 3.1% over the year to £282,000, while the South West as a whole was broadly flat. Dorset was unchanged at £325,000. Local ONS data is based on relatively few sales and reflects deals agreed several months earlier, so it tells us more about the spring than about the summer.
| Metric (ONS, July 2026) | Somerset | Dorset |
| Average price | £282,000 | £325,000 |
| Annual change | +3.1% | Little change |
| First-time buyer average | £232,000 | £254,000 |
| Home-mover average | £334,000 | £390,000 |
| Detached house average | £460,000 | £515,000 |
| Average private rent (August 2026) | £1,016 (+6.2%) | £1,056 (+4.9%) |
How Many Homes Sold This Summer? Our Local Market Data
House price indices look backwards. Our own tracking shows what is happening now. Every month we record available stock, new instructions, sales agreed and price reductions from Rightmove across 24 postcodes in South Somerset and North Dorset, covering homes priced between £200,000 and £10 million.
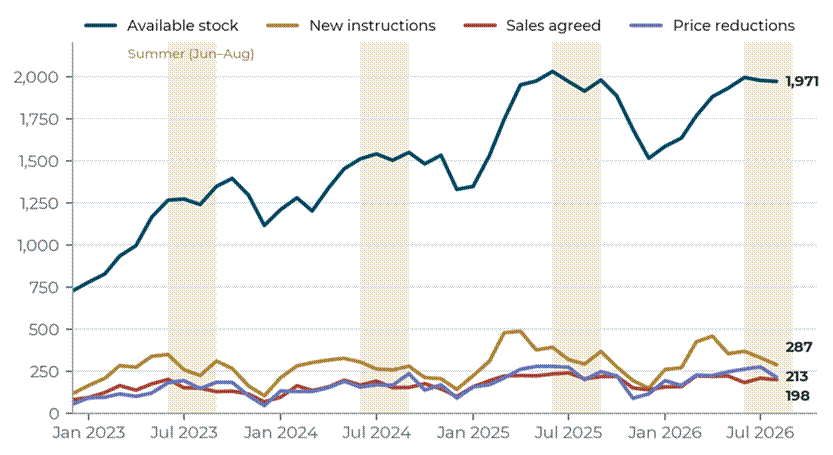
Monthly market activity since we began tracking, December 2022 – August 2026. Summer months are shaded. Source: GP Weston analysis of Rightmove data.
Supply held up. Available stock peaked at 1,994 in June, just below last June’s record of 2,030. At 1,971 in August, it was 3% higher than a year earlier. Sellers are still coming to market: 983 new instructions over the summer, compared with 1,000 in 2025, and well ahead of the 820–830 we saw in 2023 and 2024.
Demand is where the summer fell short. The 586 sales agreed over the three months were 13% down on 2025. That is still well ahead of 2023 and 2024 (498 and 507), which is a reminder that 2025 was an unusually strong year. June was the weakest month, with 181 sales agreed. That was 22% down on June 2025, and just 9.1% of available stock went under offer, the lowest June rate we have recorded. July recovered to 207, and August’s 198 was less than 3% short of last August.
Sellers are having to adjust. There were 748 price reductions, exactly the same number as last summer, but against fewer sales. For every sale agreed this summer there were 1.28 price reductions, compared with 1.11 in 2025 and 0.96 in 2024. There were more reductions than sales agreed in every one of the three months.
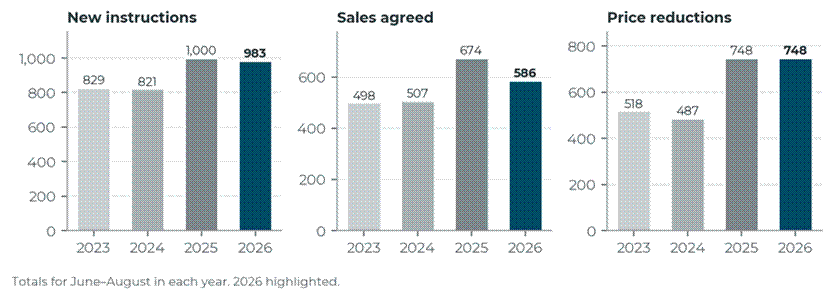
Summer (June–August) totals by year. Source: GP Weston analysis of Rightmove data.
| Summer (Jun–Aug) | 2023 | 2024 | 2025 | 2026 | 2026 vs 2025 |
| Average available stock | 1,259 | 1,518 | 1,971 | 1,981 | +0.5% |
| New instructions | 829 | 821 | 1,000 | 983 | −1.7% |
| Sales agreed | 498 | 507 | 674 | 586 | −13.1% |
| Price reductions | 518 | 487 | 748 | 748 | 0.0% |
| Sales agreed as % of stock | 13.2% | 11.1% | 11.4% | 9.9% | −1.5 pts |
| Price reductions as % of stock | 13.7% | 10.7% | 12.6% | 12.6% | −0.1 pts |
| Price reductions per sale agreed | 1.04 | 0.96 | 1.11 | 1.28 | +0.17 |
| Month (2026) | Available | New instr. | Sales agreed | Reductions | Sales agreed % of stock | Sales agreed vs 2025 |
| June | 1,994 | 367 | 181 | 261 | 9.1% | −22% |
| July | 1,977 | 329 | 207 | 274 | 10.5% | −13% |
| August | 1,971 | 287 | 198 | 213 | 10.0% | −2% |
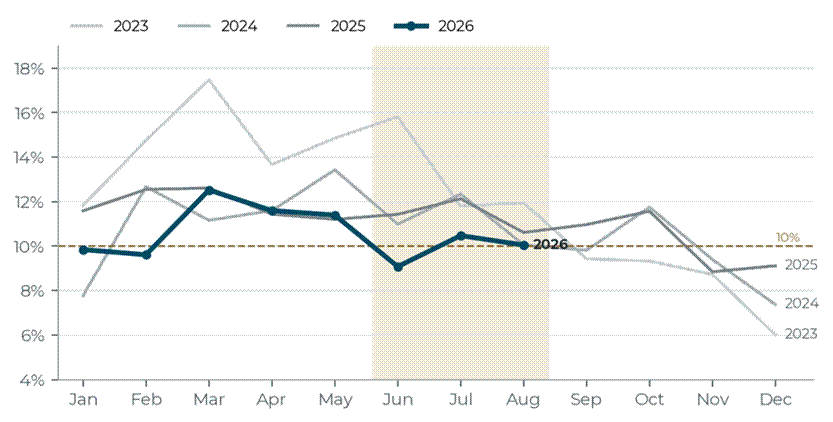
Sales agreed as a percentage of available stock, by month and year. The shaded band marks the summer; the dashed line marks 10%. Source: GP Weston analysis of Rightmove data.
Put simply, a typical home on the market this summer had roughly a one-in-ten chance of going under offer in any given month. The figure was around 11% last summer and 13% in 2023. That gap is the difference between a sale in the autumn and a listing that runs into the new year.
The Premium Rural Property Market
Higher mortgage rates hit hardest where borrowing is largest relative to the price. Equity-rich buyers, often moving from London and the South East or downsizing, are less exposed, and South Somerset and North Dorset continue to appeal to them: the landscape, the schools, the A303 and the Castle Cary line to London. The pattern we have described before still holds: homes that are well presented and realistically priced find buyers, while those launched at aspirational prices are the ones that end up in the reduction figures.
Stamp Duty & the Autumn Budget 2026
Stamp duty thresholds have not changed since April 2025, when the nil-rate band fell back to £125,000 and first-time buyer relief to £300,000 (on purchases up to £500,000). The Prime Minister has said there will be no stamp duty changes at the October Budget, which removes one reason for buyers to wait.
The main property tax already announced is the High Value Council Tax Surcharge, an annual charge on homes in England worth £2 million or more. It is due to start in April 2028, at £2,500 a year and rising to £7,500 for homes worth £5 million or more. It affects only a small number of properties in our area, but owners at the very top of the market should take it into account. With a new Chancellor who will not rule out broader tax rises, we expect some hesitation until 28 October. Once the Budget is out of the way, the run into the new year should be clearer.
Property Market Outlook: Autumn 2026
Autumn begins with a familiar seasonal pattern but an unusual economic backdrop. Rightmove’s September figures show asking prices rising for the first time since May and a pick-up in activity as families return from holiday. In our own data, the summer ended better than it began. The outlook, however, depends heavily on the energy shock and on whether inflation forces the Bank of England to act.
- Supply is plentiful. With stock close to record levels, buyers can be selective and will walk away from homes that look overpriced.
- Borrowing costs will decide the direction. If energy prices ease and swap rates fall back, mortgage pricing could improve quickly. If inflation climbs as the Bank expects, rates may stay near current levels into 2027.
- The Budget on 28 October is a near-term hurdle. With stamp duty ruled out, the effect should fall mainly on confidence rather than cost.
- Demand for West Country lifestyle property is intact. National buyer searches are up on last year, and equity-rich movers are less exposed to mortgage rates.
September usually brings a second wave of new instructions: in each of the last three years, more homes came to market in September than in August. For sellers who want to agree a sale before Christmas, the next few weeks matter. In this market, the launch price matters most of all.
At GP Weston, we believe that in a market with fewer sales but motivated buyers, the quality of the agent matters more than ever. The sellers who achieve the results they want are those who commit to professional photography and drone footage, proactive buyer matching, honest pricing advice and a single experienced point of contact throughout. These are the hallmarks of what we offer.
| “ Modern service and ideas with traditional values. In any market, that is the formula that works. GP WESTON |
Selling in Somerset or Dorset: Your Questions Answered
Is the Somerset and Dorset property market slowing down?
Yes, but it has not stalled. Across our 24 postcodes in South Somerset and North Dorset, sales agreed from June to August 2026 were 13% lower than last summer. That is still well ahead of 2023 and 2024, and by August sales were back within 3% of last year’s level. Sellers kept coming, so the slowdown is on the buyer side, driven by higher mortgage rates.
What is the average house price in Somerset and Dorset?
According to the ONS, the average price in Somerset was £282,000 in July 2026, up 3.1% on the year. In Dorset it was £325,000, unchanged on the year. Detached homes averaged £460,000 in Somerset and £515,000 in Dorset.
Is now a good time to sell my house in Somerset or Dorset?
It is a good time to sell if you price correctly. There are nearly 2,000 homes for sale in our area, so buyers have choice and they ignore homes that look overpriced. September usually brings a second wave of new listings, and Rightmove reports buyer activity picking up as families return from holiday. Homes priced right from day one sell. Rightmove found that 74% of homes sold in 2026 needed no price reduction at all.
Are house prices falling in the South West?
Not significantly. The ONS put South West prices 0.2% lower over the year to July 2026, while Somerset rose 3.1%. What has changed is the pace: homes take longer to sell, and price reductions now outnumber sales agreed each month in our area. We see a market that rewards realistic pricing, not a crash.
Will stamp duty change in the October 2026 Budget?
The Prime Minister has said there will be no stamp duty changes at the Budget on 28 October 2026. The current thresholds, in place since April 2025, remain: a £125,000 nil-rate band for home movers and £300,000 for first-time buyers on purchases up to £500,000.
About GP Weston, Estate Agents in Somerset & Dorset
GP Weston is an independent, boutique estate agency founded by James Weston and Jessica Grant Peterkin, both raised in Somerset and Dorset and each with over two decades of experience in the London and West Country property markets. Having worked for leading agencies including John D Wood, Hampton’s International, and prime Central London boutiques, James and Jessica returned to their West Country roots to offer something genuinely different: a client-first, relationship-based service free from corporate targets and red tape.
GP Weston handles residential sales and lettings across South Somerset, North Dorset, and West Dorset, and maintains connections to the London market through a curated London Properties offering. The firm makes full use of the latest technology — including drone footage, professional staging advice, and social media distribution — to present properties to the widest possible audience.
Disclaimer: This report is produced for general information purposes only and does not constitute financial, legal, or investment advice. Local market figures are GP Weston’s analysis of Rightmove data for 24 postcodes in South Somerset and North Dorset (all property types, £200,000–£10,000,000). National and economic data is sourced from publicly available sources including the Bank of England, ONS, HM Land Registry, Nationwide, Rightmove, Zoopla and Moneyfacts, and is correct to the best of our knowledge at the date of publication (September 2026). GP Weston Ltd is registered in England and Wales.